Best High-Limit Business Credit Cards in 2026: Limits From $3K Minimums to $100K+
The average business card limit is about $56,100 per Experian. Highest in 2026: Amex no-preset limits, Ink lines of $5K to $50K, Ramp and Brex at six figures.
On this page
Disclaimer: This article is for educational purposes only. Business credit limits are at the issuer’s discretion and depend on your business and personal financial profile. Limit ranges below are reported figures from the cited sources, not issuer guarantees. Credit card terms, fees, and approval criteria change frequently; verify current terms directly with the issuer before applying. This article contains affiliate links; we may earn a commission if you apply through them, at no cost to you.
Updated October 6, 2026: Merged our business credit card limits guide into this page, adding the reported average limit, limits by business profile, and how corporate cards reach six figures.
The business credit cards with the highest limits are no-preset-spending-limit (NPSL) charge cards: the Amex Business Platinum, the Amex Business Gold, and the Capital One Spark Cash Plus, none of which carries a fixed credit line. Among revolving cards the Chase Ink Business Preferred is the high-limit pick, while fintech cards like Ramp and Brex size your limit off your business cash balance instead of a personal credit score, so they can go far higher for cash-rich companies.
For scale: business credit card limits run from a reported $3,000 minimum line on entry Chase Ink cards to six figures on balance-based corporate cards, with the reported average small business limit sitting around $56,100 per Experian data cited by WalletHub. What you actually get depends on which of two underwriting worlds you apply in: traditional business cards (Chase Ink, Amex) size the limit mostly to your personal credit and combined income, while corporate charge cards (Ramp, Brex) size it to the cash in your business bank account.
For a high earner with any business income, the most underused source of credit capacity is a business credit card. A business card adds a separate, often higher line that usually stays off your personal credit report, does not count against your personal utilization, and (for most issuers) does not add to your Chase 5/24 count. If you have consulting income, a side venture, rental property, or RSU-funded angel investments, you almost certainly qualify.
This guide covers which business cards approve the highest limits, what limits look like by business profile, how no-preset-limit charge cards actually work, and how to qualify as a sole proprietor. It is the business companion to our Credit Cards With the Highest Starting Limits and Credit Card Limits by Income guides, both of which cover personal cards.
Key Facts: High-limit business credit cards in 2026
- The reported average small business credit card limit is about $56,100 (Experian data via WalletHub); Forbes Advisor reports business limits run roughly double consumer limits
- No-preset-limit (NPSL) charge cards (Amex Business Platinum and Gold, Capital One Spark Cash Plus) flex highest among traditional cards because they have no fixed line, and they are not unlimited
- Reported minimum credit lines: $3,000 on Chase Ink Business Cash and Unlimited, $5,000 on Ink Business Preferred, $10,000 on Ink Business Premier; the Ink Preferred often exceeds $25,000 for strong profiles
- Six-figure limits are a corporate charge card phenomenon: Ramp and Brex size limits to business cash balance, with NerdWallet reporting 10x to 30x traditional limits
- Most business cards do NOT report to personal credit, so they add capacity without raising personal utilization; Capital One is the major exception
- Chase, Amex, and Capital One NPSL business cards do not add to Chase 5/24, but Chase still requires you to be under 5/24 to be approved
- You can apply as a sole proprietor with just an SSN; gig and side income count
The Best Business Credit Cards With High Limits in 2026
The table below ranks the high-limit options by how each card’s limit is set. The three NPSL charge cards have no fixed line at all, which is why they top the list for raw spending power.
| Card | Issuer | Annual fee | Limit type and how it is set |
|---|---|---|---|
| Amex Business Platinum | Amex | $895 | No preset spending limit; flexes with your purchase, payment, and credit history; pay in full |
| Amex Business Gold | Amex | $375 | No preset spending limit; Pay Over Time available on eligible charges |
| Capital One Spark Cash Plus | Capital One | $150 | No preset spending limit; adapts to spending behavior, payment history, and credit profile |
| Chase Ink Business Preferred | Chase | $95 | Revolving; $5,000 reported minimum line, often higher for strong profiles |
| Chase Ink Business Unlimited | Chase | $0 | Revolving; $3,000 reported minimum, case-by-case line |
| Chase Ink Business Cash | Chase | $0 | Revolving; $3,000 reported minimum, case-by-case line |
| Ramp | Fintech | $0 | Charge; limit set from real-time business cash and financials; no personal guarantee |
| Brex | Fintech | $0 | Charge; limit set from business cash balance; needs a US EIN and US incorporation |
The annual fees above are confirmed on each issuer’s official page, including the $0 card fee on Ramp and Brex. Chase does not publish a fixed minimum credit line for the Ink cards, so treat the reported floors (from WalletHub) as approximate; strong applicants regularly land well above them. Ramp and Brex are covered in their own section below, because their limits run on entirely different math.
Business Credit Card Limits: The 2026 Map
What limits look like by business profile, using reported figures from the sources listed at the bottom of this page.
| Business profile | Reported limit picture | Where those limits live |
|---|---|---|
| New sole proprietor or side business | Reported minimum lines of $3,000-$5,000; approval leans on personal income and FICO | Ink Business Cash/Unlimited ($3K reported minimum), Ink Business Preferred ($5K reported minimum) |
| Established small business, six-figure revenue | Reported average around $56,100; Ink Preferred reported to exceed $25K for strong profiles | Ink Business Preferred, Amex Business Gold (no preset limit) |
| Startup or business holding $25K-$50K+ in cash | Limit sized to bank balance; reported 10x-30x traditional limits | Ramp ($25K minimum cash to qualify), Brex ($50K minimum balance for funded startups) |
| Well-capitalized company, $500K+ in the bank | Reported six figures, up to hundreds of thousands, scaling with cash | Ramp, Brex, Amex Business Platinum (no preset limit) |
Business card limits live on different ladders
Typical reported limits by business profile, 2026
Share or embed this chart
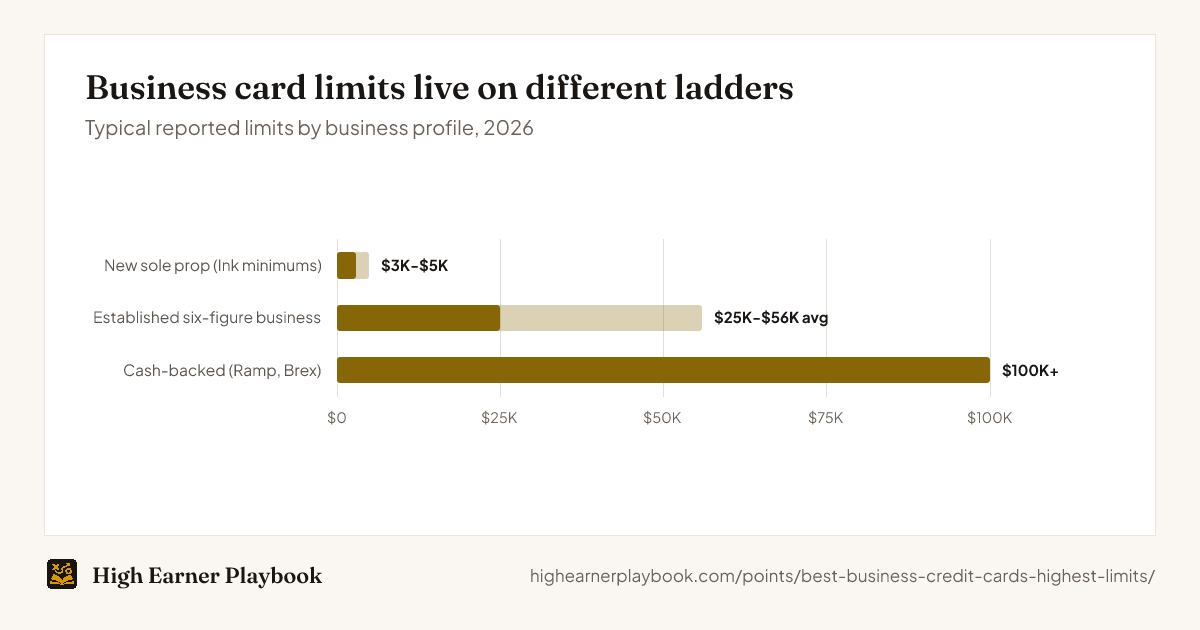
The single most useful thing to understand about this table: the first two rows and the last two rows are different products underwritten on different math. A traditional Ink or Amex business card will not give a bootstrapped LLC a $200,000 line no matter how good the owner’s FICO is. A corporate charge card will, if the cash is there.
How Business Card Limits Are Set (and Why Personal Income Still Matters)
Business cards split into two structures, and the difference drives how high your limit can go.
Revolving cards (Chase Ink Business Preferred, Ink Business Unlimited, Ink Business Cash) work like a personal card: a fixed credit line you can carry a balance against.
No-preset-limit (NPSL) charge cards (Amex Business Platinum, Amex Business Gold, Capital One Spark Cash Plus) have no fixed line at all. Spending power is evaluated per transaction rather than set once at approval, so capacity can grow as you use and pay the card, and can contract if payments slip. These cards generally must be paid in full each month.
For traditional small business cards of either structure, the underwriting inputs look more like a personal application than most owners expect. Forbes Advisor reports four drivers of the business limit:
- Personal credit. Good personal credit makes it easier to qualify for higher business limits. Your FICO score does the same work it does on a personal application.
- Business credit history. A business credit profile with on-time tradelines helps, though thin business files are normal and not disqualifying.
- Income and revenue. Issuers consider both personal income and business revenue. For a new sole proprietorship, personal income carries most of the weight.
- Existing debt. High utilization or heavy obligations on either side of the ledger caps the line.
Time in business matters too (roughly two or more years is the comfortable zone for lenders), and an existing banking relationship with the issuer helps, the same way it does on the personal side. Nearly every traditional small business card also includes a personal guarantee, which Bankrate describes as a clause in the card agreement outlining your personal liability for the account. The business gets the card; you backstop it. That is why a strong personal FICO does most of the work on your first business card.
Corporate charge cards throw most of this out. Ramp sets limits from real-time business financials: the cash balance in your linked bank accounts, liquid assets, debt, spending patterns, annual revenue, and industry, with no personal guarantee required. Brex determines limits through cash-based or revenue-based underwriting tied to your connected account balances, and the limit is dynamic by design: it moves as your balances and financial performance move.
What Limits Do Traditional Business Cards Give You?
The reported floor for the Chase Ink family, per WalletHub: $3,000 minimum lines on the Ink Business Cash and Ink Business Unlimited, $5,000 on the Ink Business Preferred, and $10,000 on the Ink Business Premier. Ramp’s analysis of the Ink Business Preferred reports the same $5,000 typical start, limits potentially exceeding $25,000 for stronger profiles, and a ceiling around $50,000 across the Ink cards.
Those are floors and reported outer bounds, not what a strong applicant should expect. User-reported approval data clusters in the $20,000 to $50,000 range for the Ink Business Preferred when the applicant brings high personal income, a 740+ FICO, and existing high limits. The same anchor effect from the personal side applies: your highest existing line, personal or business, benchmarks the new approval.
On the Amex side, the Business Gold ($375 annual fee) and Business Platinum ($895) are not fixed-limit cards at all. They carry no preset spending limit, covered in its own section below, which is exactly why they show up in every high-limit conversation despite never publishing a number.
Corporate Cards: Where Six-Figure and $500K Limits Actually Live
Search data shows people hunting for a “corporate credit card with a $500K limit.” Here is the honest version of that answer: no issuer advertises a $500,000 limit, and no reputable source publishes one. What exists is a category of corporate charge cards whose limits scale with your cash balance, and for well-capitalized companies those limits are reported to reach six figures and beyond. WalletHub puts the outer bound at “hundreds of thousands of dollars” depending on credit, income, and business revenue.
The two names that matter:
Ramp. To qualify, Ramp requires at least $25,000 in cash in a linked U.S. business bank account, and the business must be a registered entity (corporation, LLC, or LP; sole proprietors are not eligible). The limit comes from real-time business financials with no personal guarantee. NerdWallet reports Ramp offering up to 30 times higher credit limits than traditional business cards. Ramp also publishes a self-serve lever most cards lack: deposit funds into a locked Reserve Account and your 30-day card limit increases on a 1:1 basis, no credit review required.
Brex. Brex requires a U.S.-incorporated entity with an EIN, and for funded startups a minimum cash balance of $50,000. Limits come from cash-based or revenue-based underwriting: connected bank balances, bank statements, or financial statements. For its daily-payment card, Brex states limits are based on the aggregate balance of your Brex business account. NerdWallet reports Brex limits running 10 to 20 times higher than traditional small business corporate cards. Brex’s own marketing goes further, claiming limits that start around $50,000 and climb well into six figures; treat that as a vendor claim rather than a neutral report.
The mechanics explain the whole category. These are charge cards paid in full (daily or monthly), so the issuer’s exposure window is short, and the limit is collateralized in practice by visible cash. That is why a startup that just raised $5M can hold a limit no bank would issue it, and why the limit drops if the balance drops. If your business does not hold meaningful cash, or you run it as a sole proprietor, this category does nothing for you, and the traditional cards above remain the play.
What “No Preset Spending Limit” Actually Means
The Amex Business Platinum and Business Gold have no preset spending limit, which is neither a limit nor unlimited. Amex’s own explanation: the amount you can spend adapts based on factors such as your purchase, payment, and credit history. Amex states explicitly that no preset limit does not mean unlimited spending, and that in some cases it may assign a specific spending limit to an account.
In practice, three things follow from that structure:
- Your capacity is a moving number, not a line. It grows with regular use, on-time payments, and a strong credit profile, and it can contract if payments slip or balances build elsewhere.
- You can check it before a big charge. Amex’s Check Spending Power tool (in the app or online account) lets you test whether a specific purchase amount would be approved before you run it. This is the honest answer to “what is my Amex business limit”: whatever Check Spending Power approves today.
- Large atypical charges can decline. The adaptive model is anchored to your history, so a first-ever $80,000 charge on a card that has only seen $10,000 months is exactly the transaction to pre-check.
For a business with lumpy spend (a big ad buy, an inventory purchase, a tax payment), this structure often beats a fixed line one tier taller than your normal month. The Business Gold also offers Pay Over Time on eligible charges up to a Pay Over Time limit, so it behaves as a hybrid rather than a pure charge card.
Rewards and Welcome Offers on High-Limit Business Cards
A high limit pays off most when the card also earns well on the spend you route through it. Here is what each card earns and its current welcome offer, with every figure confirmed on the issuer’s official page.
| Card | Rewards | Welcome offer |
|---|---|---|
| Amex Business Platinum | 5X on flights and prepaid hotels booked on amextravel.com; 2X on eligible purchases in key business categories or on single purchases of $5,000 or more, on up to $2 million per year; 1X on everything else | As high as 300,000 Membership Rewards points after $20,000 in the first 3 months (personalized; offers vary) |
| Amex Business Gold | 4X in your 2 highest-spend categories of 6 eligible, on up to $150,000 in combined purchases per year, then 1X; 3X on flights and prepaid hotels booked on amextravel.com | As high as 200,000 Membership Rewards points after $15,000 in the first 3 months (personalized; offers vary) |
| Capital One Spark Cash Plus | 2% cash back on every purchase; 5% on hotels and rental cars booked through Capital One Travel | $2,000 cash bonus after $30,000 in the first 3 months |
| Chase Ink Business Preferred | 3X on travel, shipping, internet/cable/phone, and advertising on the first $150,000 in combined purchases per anniversary year, then 1X; 1X on everything else | 100,000 bonus points after $8,000 in the first 3 months |
| Chase Ink Business Unlimited | 1.5% cash back on every purchase | $1,000 cash back after $8,000 in the first 4 months (elevated from $750 as of July 2026) |
| Chase Ink Business Cash | 5% on the first $25,000 at office supply stores and on internet/cable/phone each year; 2% on the first $25,000 at gas stations and restaurants; 1% on everything else | $1,000 cash back after $8,000 in the first 4 months (elevated from $750 as of July 2026) |
The Spark Cash Plus has a twist for heavy spenders: its $150 annual fee is refunded every year you spend at least $150,000, and it pays an extra $2,000 bonus for every $500,000 you spend in your first year.
Do High-Limit Business Cards Report to Your Personal Credit?
This is the feature that makes business cards so useful for high earners: a large balance on a business card usually does not touch your personal credit report or your personal utilization ratio. But it is issuer-specific.
| Issuer | Reports ongoing activity to personal credit? |
|---|---|
| Chase | No (only on serious default) |
| Amex | No (only on serious delinquency or default) |
| Capital One | Yes for most business cards (exceptions: Spark Cash Plus, Venture X Business) |
| Citi, Bank of America, Barclays, U.S. Bank | Generally no |
| Discover | Yes |
The practical takeaway: if you want to put heavy spend on a business card without spiking your personal utilization, Chase and Amex are the clean choices. With Capital One, assume a standard business card behaves like a personal card on your report unless it is one of the two NPSL exceptions.
Business Cards and Chase 5/24
Chase’s 5/24 rule denies most applicants who have opened five or more personal credit cards in the past 24 months. Business cards interact with it in a way that trips up even experienced applicants:
- They do not add to your 5/24 count. Business cards from Chase, Amex, and the Capital One NPSL lineup are not reported to personal credit, so opening one does not increase your count.
- But Chase business cards still require you to be under 5/24 to be approved. You can use them to grow credit capacity without burning 5/24 slots, but you cannot get approved for a Chase business card once you are already at or above five.
- Most Capital One business cards are the exception again: because they report to personal credit, they do add to your 5/24 count. Discover and TD business cards also add.
If you are managing a card strategy around 5/24, business cards from Chase and Amex are the way to keep adding capacity. For how many to open and in what order, see How Many Business Credit Cards Can You Have?, and for the earning side of the stack, Best Business Credit Cards for High Earners.
How to Qualify as a Sole Proprietor
You do not need an LLC, a registered business name, or an EIN. The vast majority of high earners with side income qualify as a sole proprietor:
- Apply with your SSN. An EIN is optional and can be added later; most sole-proprietor applications use your SSN.
- Use legitimate side income. Consulting, freelancing, gig work (driving, delivery), content, tutoring, rental income, and similar all count as business income.
- List your details honestly. Business name is your own name or a DBA, business address can be your home, and you report estimated gross annual revenue. A low or new revenue figure does not automatically disqualify a first application.
- Lean on personal credit. Approval and initial limits draw heavily on your personal FICO. The high 600s and above is the common benchmark for a clean approval.
High earners with RSU-funded side ventures or consulting income are an especially strong fit, and asset-rich households layering a business line onto the personal high net worth card stack are another. Our Best Credit Cards for Tech Executives guide covers how that side income opens up the business-card layer of a stack.
How to Raise a Business Credit Card Limit
The levers, in rough order of effect:
- Update your revenue with the issuer. Business limits key on reported revenue the way personal limits key on income. A business that has grown since the application is underwriting itself at last year’s number until it says otherwise.
- Wait for seasoning, then ask. Forbes Advisor reports increases are likelier once the account is at least six months old, with on-time (ideally large or full) payments and rising revenue behind the request.
- Keep reported utilization down. High balances on either your personal or business profile cap the next decision, per the same Forbes factor list.
- On corporate cards, move the cash. Ramp reviews limits against your company’s financial profile on an ongoing basis, and its Reserve Account raises the 30-day limit 1:1 with deposited funds. Brex states the best way to unlock a higher limit is connecting all bank accounts where the business holds cash, since the limit is computed from what it can see.
- Add a second line instead of growing the first. Business approvals draw on a separate pool from your personal cards, and each new line adds capacity without a limit-increase request. The math on stacking is in How Many Business Credit Cards Can You Have?
Moving Limits Between Business Cards
Chase publishes the rules for this via its Credit Line Exchange: you can move available credit between Chase business cards owned by the same authorizing officer, online, in $100 increments, up to three times per month, with changes usually immediate. Two constraints matter. Moves only work between cards of the same type (business to business or personal to personal, never across), and a card opened within the last 12 months cannot give up line. Moves between revolving and pay-in-full business cards require a phone call rather than the online tool.
This is the quiet fix for a common situation: a legacy Ink card hoarding a $40,000 line while the card you actually spend on sits at $12,000. Reallocating costs no hard pull and reshapes your capacity to match your spend.
Common Mistakes
- Assuming NPSL means unlimited. It does not. Amex and Capital One review each charge, and large purchases can be declined. Use Amex’s Check Spending Power tool before a big buy.
- Putting a large tax payment on a charge card you cannot pay in full. NPSL charge cards (Amex Business Platinum and Gold, Spark Cash Plus) require pay-in-full; you cannot carry that balance like a revolving card.
- Forgetting that Capital One reports most business cards to personal credit. A big balance on a standard Capital One business card spikes your personal utilization and counts against 5/24, unlike Chase and Amex.
- Misreading the Chase 5/24 rule. Business cards do not add to your count, but you must still be under 5/24 to be approved for a Chase business card.
- Chasing a $500K corporate card without the cash behind it. Ramp and Brex limits track your bank balance; a thinly capitalized business will not get there.
- Overstating Bank of America Preferred Rewards for Business. It boosts rewards and lending rates, not card credit limits. Do not count on it to raise a card line.
What to Do This Week
- Confirm your side income qualifies. Any consulting, gig, freelance, or rental income is enough to apply as a sole proprietor.
- Pick the structure you need. For the highest flexible spending power, an NPSL charge card; for a carryable revolving line, the Ink Business Preferred; for a cash-rich registered company, Ramp or Brex.
- Keep heavy spend off your personal credit. Favor Chase and Amex business cards; treat standard Capital One business cards as if they report to personal credit.
- Check your 5/24 status before any Chase business application, since approval still requires being under five.
- Track every line in one place so you know your true combined capacity across personal and business cards.
Frequently Asked Questions
What are the best business credit cards with high limits?
The best high-limit business credit cards are no-preset-spending-limit (NPSL) charge cards: the Amex Business Platinum ($895 annual fee), the Amex Business Gold ($375), and the Capital One Spark Cash Plus ($150). None carries a fixed credit line, so spending power flexes with your purchase, payment, and credit history. For a revolving line you can carry a balance against, the Chase Ink Business Preferred ($95) is the standard pick. Ramp and Brex set their limits from your business cash balance instead of a credit score, which can run far higher for cash-rich businesses.
What is the average business credit card limit?
The most widely cited figure is about $56,100, an average reported by WalletHub based on Experian data. There is no official number: Forbes Advisor notes that issuers do not publish an average business credit card limit, but reports that small business owners have had roughly double the revolving credit access of consumers, whose average across all cards was about $29,855 in Experian’s 2023 data. In practice the range is enormous, from reported $3,000 to $5,000 minimum lines on Chase Ink cards up to six-figure limits on balance-based corporate cards.
What is the highest business credit card limit?
No issuer publishes a maximum, and WalletHub reports that business limits can reach hundreds of thousands of dollars depending on credit, income, and business revenue. Among traditional cards, reported Chase Ink limits top out around $50,000. The genuinely high limits live on balance-based corporate charge cards: NerdWallet reports Ramp offering up to 30 times higher limits than traditional business cards and Brex 10 to 20 times higher, because both size the limit to the cash in your business bank accounts rather than to a personal credit profile. A company holding seven figures in cash can see a six-figure limit that no traditional application would produce.
Can you get a corporate credit card with a $500,000 limit?
No card advertises a $500,000 limit, but balance-based corporate cards can reach that territory because the limit scales with your cash. Brex determines limits through cash-based or revenue-based underwriting tied to connected account balances, and Ramp sets limits from real-time business financials including linked bank balances, with a Reserve Account option that raises the 30-day limit dollar for dollar on deposited funds. WalletHub reports business limits reaching hundreds of thousands of dollars for qualified companies. The honest framing: a $500,000 limit is a function of holding roughly that much (or more) in verifiable cash, not of finding the right application.
What credit limit does the Chase Ink Business Preferred start with?
The Ink Business Preferred carries a reported minimum credit line of $5,000, per WalletHub, and Ramp’s analysis of the card reports the same $5,000 typical starting point with limits potentially exceeding $25,000 for stronger profiles and a reported ceiling around $50,000 across the Ink family. WalletHub’s reported minimums for the other Ink cards: $3,000 on the Ink Business Cash and Ink Business Unlimited, and $10,000 on the Ink Business Premier. User-reported approval data for high earners with strong personal credit clusters well above the minimums, commonly in the $20,000 to $50,000 range.
How are business credit card limits determined?
For traditional small business cards, Forbes Advisor reports four drivers: your personal credit, your business credit history, income and revenue (personal income plus business revenue), and existing debt. Time in business and an existing banking relationship also help. Nearly all traditional business cards also require a personal guarantee, which Bankrate describes as a clause making you personally liable for the account. Balance-based corporate cards work differently: Ramp underwrites on linked bank balances, liquid assets, industry, and credit bureau data with no personal guarantee, and Brex uses cash-based or revenue-based underwriting with limits that adjust dynamically as balances change.
Do business credit cards have higher limits than personal credit cards?
Generally yes. Forbes Advisor reports that business credit cards tend to feature higher limits than personal cards, and that small business owners have had roughly double the revolving credit access of the average consumer. The reported average business card limit of about $56,100 (Experian data via WalletHub) is nearly twice the reported average consumer limit. The bigger structural advantage is separation: business limits come from a separate pool that does not share with your personal cards, so a business approval adds entirely new capacity.
What does no preset spending limit actually mean?
No preset spending limit (NPSL) means the card has no fixed credit line, not that it is unlimited. Amex and Capital One evaluate each charge against your spending, payment, and credit history rather than against a set line. NPSL charge cards are designed to be paid in full each month, though the Business Gold offers Pay Over Time and the Spark Cash Plus lets you carry part of the balance with interest. Amex’s Check Spending Power tool lets you test whether a specific purchase would be approved before you run it.
Do high-limit business credit cards report to your personal credit?
Most do not report ongoing activity to your personal credit, which is why they add spending capacity without raising your personal utilization. Chase and Amex business cards report to personal credit only on serious default. The major exception is Capital One: most Capital One business cards report ongoing balances and payments to your personal credit, with the no-preset-limit Spark Cash Plus and Venture X Business being the exceptions that do not.
Can you get a high-limit business credit card as a sole proprietor?
Yes. You can apply as a sole proprietor using your Social Security number, with no LLC, registered name, or EIN required. Gig, consulting, freelance, and other side income all count as legitimate business income. On the application you list your own name as the business name, your home address, and your estimated gross revenue. Approval and your starting limit lean heavily on your personal credit, so a FICO in the high 600s or above is the usual benchmark.
Do high-limit business cards count toward Chase 5/24?
Business cards from Chase, Amex, and Capital One’s no-preset-limit lineup do not add to your 5/24 count because they are not reported to personal credit. But there is a catch: Chase still requires you to be under 5/24 to be approved for its business cards. Most other Capital One business cards do add to 5/24, as do Discover and TD business cards.
Bottom Line
The reported average business card limit is about $56,100, but the average hides the split that actually matters. Traditional business cards (Ink, Amex) underwrite you: personal credit, combined income, a personal guarantee, reported floors of $3,000 to $10,000, and strong-profile approvals reported into the $20,000 to $50,000 range, with Amex’s no-preset-limit cards flexing above that for proven spenders. Corporate charge cards (Ramp, Brex) underwrite your bank balance: 10x to 30x traditional limits per NerdWallet, six figures and reportedly hundreds of thousands for well-capitalized companies, no personal guarantee, paid in full.
Nobody sells a $500,000 limit. Companies holding $500,000 get offered one.
Sources:
- WalletHub: average business credit card limit (Experian data) and Chase Ink minimum credit lines
- Forbes Advisor: business credit card limit factors and business-vs-consumer comparison
- NerdWallet: high-limit business cards, Ramp and Brex multiples, no-preset-spending-limit cards, and Chase Ink Business Preferred review
- American Express: what no preset spending limit means and no preset spending limit explained
- Chase: Credit Line Exchange rules and can you get a business credit card without a business?
- Ramp: card and limit model, application requirements, business limits and Reserve Account, and Ink Business Preferred limit analysis
- Brex: account requirements and how credit limits work
- Bankrate: personal guarantees on business cards
- Doctor of Credit: which business cards report to personal credit
- The Points Guy: business credit cards that affect personal credit and the ultimate guide to Chase 5/24
Typical-limit ranges are reported figures from the sources above, not issuer-published numbers. Individual approvals vary.
Related reading:
- Credit Card Limits by Income
- Credit Cards With the Highest Starting Limits
- Best Business Credit Cards for High Earners in 2026
- How Many Business Credit Cards Can You Have?
- Best Credit Cards for Tech Executives with Heavy RSU Vesting
- Building Your Credit Card Points Strategy
- Are Credit Card Rewards Taxable?
Related Articles
Points
Credit Card Limit Statistics 2026: Average Limits by Score, Age, and Account, With $5.56 Trillion in Total Lines
Credit card limit statistics for 2026: $5.56 trillion in total limits, $8,400 average per account, $13,200 for 800+ scores, $6,427 on new cards. 60+ sources.
Points
How Many Business Credit Cards Can You Have? (2026)
How many business credit cards can you have? Per-issuer limits at Chase, Amex, and Capital One, how business cards interact with 5/24, and how to build a stack.
Points
Credit Card Limits by Income: What $75K, $100K, $150K, $300K, and $500K+ Typically Get You in 2026
Credit card limits by income in 2026: reported starting limits of $10K-$20K at $75K, $15K-$25K at $100K, $20K-$25K at $150K, $30K-$50K at $300K, with sources.